

Uber Pro Card
by Branch Messenger
4.9
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.9
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
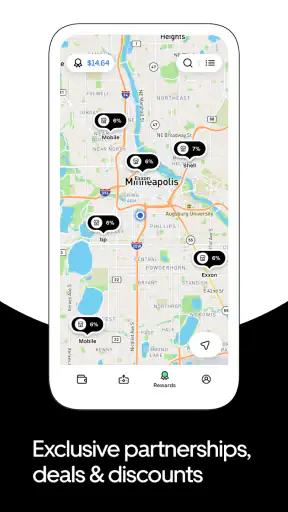
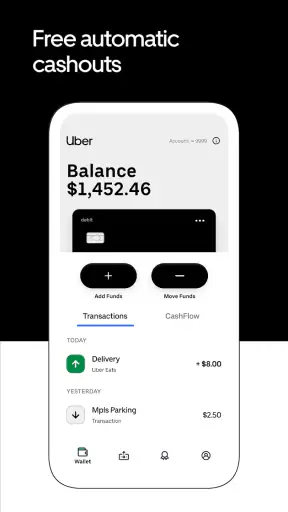
 Analysis by Getfullapps
I approached Uber Pro Card as a working driver would: not as a general banking app, but as a finance tool built around getting paid from Uber work and keeping that money easier to manage. That distinction matters. If your income comes through Uber and you want a dedicated place to separate driving money from household spending, the app has a clear purpose. If you are looking for a complete replacement for a traditional bank, my view is more cautious.
The app is developed by Branch Messenger and is free to use, with an Everyone content rating. It sits in the finance category, and its store summary, “Keep more of what you earn,” captures the central idea without explaining all the practical decisions a driver still has to make. I found the most useful way to judge it was to ask whether it reduces friction between finishing a trip, receiving earnings, and using that money responsibly.
Its current version is 2026.8.2, and the app requires Android 10 or later. That relatively modern requirement is worth checking before installing, especially if you keep an older phone for work. The product has been available since July 27, 2022, so it is not a brand-new experiment. Its presence on the platform is substantial: it has passed one million installs, with an average rating of 4.9 from around eighty-two thousand ratings and roughly six thousand reviews.
How the card fits into a driver’s everyday money routine
I’d treat the card as one clearly defined part of a driver’s money routine, rather than a shared household account: that makes it easier to know which funds relate to Uber work and which belong to everyday family spending. The next question is how to set that boundary in practice, especially when more than one person uses the same device.
A focused account rather than an all-purpose financial hub
The strongest part of the experience is its focus. The Uber Pro Card is intended for people whose earnings are connected to Uber driving, so the app makes more sense when viewed as a work-money companion. Instead of allowing trip income to disappear into the same balance used for rent, subscriptions, groceries, and personal transfers, I can treat it as a separate lane for earnings from the road.
That separation can be surprisingly useful. A driver may want to leave fuel money untouched, move a portion toward taxes, or simply see whether a busy week actually produced enough after everyday driving costs. The app does not magically calculate profitability for you, but a dedicated earnings destination gives you a cleaner starting point than one mixed bank balance.
I would not confuse that with full financial planning. The app is most helpful at the point where earnings arrive and become available for spending or organizing. It is less likely to replace a budgeting system that tracks mileage, maintenance, insurance, quarterly tax planning, and household bills in detail. Those jobs require habits and tools beyond a card-centered finance app.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Where it is more practical than the usual alternative
The usual alternative is sending all Uber earnings to an existing checking account. That approach is familiar and may be perfectly adequate if your bank already gives you the alerts, categorization, and access you need. The disadvantage is that work income becomes difficult to distinguish from everything else. When the month gets busy, it is easy to spend money intended for fuel or forget how much driving actually contributed.
A separate card can make that boundary visible. I can use it for work-related purchases, check the balance before accepting a long shift, and keep personal spending on another account. That is not a glamorous feature, but it is a meaningful workflow improvement for anyone who wants less mental bookkeeping.
The trade-off is concentration. If you rely on one dedicated card for driving income, you should still maintain a backup payment method. A card-focused setup is convenient when everything works as expected, but a cautious user will not make it the only way to pay for fuel, food, or urgent expenses. Keeping another account available is sensible financial housekeeping, not a criticism unique to this app.
A realistic week with the app
Imagine I drive several evenings after my regular job. At the end of a shift, the money associated with that work belongs in the same place, rather than being mixed immediately with my salary. The next morning, I can look at the work balance and decide how much is available for fuel, how much should remain untouched, and whether I need to transfer money elsewhere for a bill.
On a heavier weekend, that same separation helps me compare the result of driving with the costs that came with it. I still need my own records for fuel, maintenance, and taxes, but I am less likely to mistake a higher balance for pure profit. This is one of the app’s less obvious strengths: it can encourage better decisions simply by giving work earnings a distinct home.
For a full-time driver, the value is more operational. The card can become part of a repeatable routine: finish driving, review the available money, reserve what is needed for the next shift, and move the rest according to a personal plan. The app does not replace judgment, but it can make that routine easier to repeat.
What the current version says about the product’s direction
The current version, 2026.8.2, shows that the product is still being maintained rather than left in its original state. I see that as a positive sign for an app handling work-related finances. Drivers depend on basic reliability, and an actively maintained application is more reassuring than one that appears frozen after launch.
At the same time, a version number alone does not tell me that every daily frustration has disappeared. Updates can refine the experience without changing the larger question of whether the card fits a particular driver’s financial setup. I would treat the current release as evidence of ongoing product evolution, not as a promise that the app has become a complete banking replacement.
What existing users may notice over time
For someone already using the card, continued updates are most valuable when they reduce small points of friction: checking money quickly, understanding what is available, and completing routine actions without hesitation. Those details matter more than flashy additions because drivers often open the app between trips or at the end of a tiring shift.
Existing users should also reassess their workflow occasionally. An app that worked well when driving was occasional may need a different setup when driving becomes a primary income source. I would review whether the card is still being used for the right expenses, whether a backup account is in place, and whether personal records are keeping up with work costs.
The important distinction is between the app’s convenience and the user’s financial safeguards. A smoother interface can make access easier, but it should not encourage someone to stop tracking expenses or to treat every available dollar as spendable. The best results come when the app handles the payment side while the driver maintains a separate record of business costs.
Practical habits that make the card more useful
- Give the balance a job. Decide in advance whether the card is mainly for fuel, general work expenses, a holding place for earnings, or a combination. Without that rule, a separate account can become just another unstructured spending account.
- Check money before a shift, not only after it. Knowing what is available for fuel and meals can prevent an unnecessary transfer or an awkward payment problem while working.
- Keep tax and vehicle records elsewhere. A card balance is not the same as a profit statement. Save the information needed for mileage, fuel, repairs, insurance, and other costs in a dedicated record.
- Maintain a fallback. Keep another payment option available for emergencies, phone problems, or situations where the card is not the most convenient choice.
These habits are not hidden buttons inside the app, but they are the practical layer many people miss when choosing a financial tool. The card is more useful when it supports a clear system instead of becoming the system by itself.
Who should seriously consider it
I think the app is a strong candidate for active Uber drivers who want to isolate driving income from personal money. It is especially suitable for someone who struggles to see how much work income remains after ordinary spending, or for a driver who wants a simple dedicated payment route without opening a complicated financial setup.
It may also suit part-time drivers who want a low-effort way to keep occasional earnings visible. Even a few shifts can create confusion when payments land in a main account and are spent gradually. A separate card gives those earnings a clearer identity, which can make it easier to decide whether driving is worth continuing.
Who should choose another arrangement
I would be less enthusiastic for someone who already has a bank account with excellent spending controls and a reliable way to separate gig income. Adding another card may create more logins, more balances, and more opportunities to lose track of money. In that case, the dedicated Uber connection may not outweigh the convenience of staying with an established setup.
It is also not the right answer for a person seeking advanced investing, detailed accounting, or a broad financial dashboard. Drivers with complex business finances may prefer a traditional bank combined with bookkeeping software, because those tools are designed to organize a wider financial picture. The Uber Pro Card is more focused and therefore less comprehensive.
Limitations I would keep in mind
The first limitation is that the app’s usefulness depends heavily on your relationship with Uber work. Its focused design is an advantage for drivers, but it narrows the audience. Someone who rarely drives or earns from several unrelated platforms may find a general-purpose account more flexible.
The second is the risk of mistaking convenience for financial clarity. Seeing money in a dedicated balance does not tell you how much remains after fuel, tires, servicing, insurance, or taxes. A driver who wants a true earnings picture must still do that work separately. I consider this the most important caution because a clean-looking balance can create false confidence.
The third is device compatibility. Android users need Android 10 or later, so an older handset may prevent installation or require a phone upgrade. For a work app, that can be an annoying practical barrier, particularly when someone keeps an older device as a backup. I would check the phone before planning to depend on it during a working week.
There is also a broader dependency issue. When a financial routine is tied closely to one work platform, changes in driving activity can make the arrangement less useful. If you stop driving, switch to another income source, or begin combining several gig platforms, reassess whether the card still deserves a central place in your finances.
Questions I would answer before installing
Is it free? The app is listed as free, which removes an obvious barrier to trying it. I would still approach any financial product by reading the terms shown during setup and checking the details attached to the card itself before making it part of a larger money routine.
Can it replace my normal bank account? I would not assume that. It can serve as a dedicated place for Uber-related earnings and spending, but a normal bank account may remain better for household bills, broader account management, and a financial setup that is not tied to one source of work.
Is it suitable for occasional drivers? Yes, potentially. Occasional drivers can benefit from separating side-income money, especially if their primary account becomes confusing. The benefit is smaller if they already use a disciplined budgeting method that keeps gig earnings distinct.
Do I still need to track expenses? Absolutely. The app can help you manage where money goes, but it should not be treated as a substitute for records of mileage, fuel, maintenance, insurance, and tax-related information. That distinction is essential for anyone driving regularly.
What should I watch after installing? I would watch how quickly the app becomes part of a reliable routine, whether the balance is easy to understand, and whether it genuinely reduces transfers and confusion. I would also pay attention to future releases for improvements that make everyday access clearer, while separating those confirmed changes from hopes about features that may never arrive.
My final take for drivers
After looking at the app as a working tool rather than a generic finance download, I see a sensible product with a deliberately narrow role. The best reason to use it is not the promise of a complete financial life in one place. It is the simpler benefit of giving Uber earnings their own route, their own balance, and a clearer connection to the costs of driving.
The high user response and broad adoption make it easier to take seriously, while the ongoing version history suggests that Branch Messenger continues to maintain the experience. Still, popularity does not remove the need for a backup payment method or proper expense records. Those are the responsibilities that remain with me as the user.
My recommendation is straightforward: if you drive for Uber and want a dedicated way to organize work money, this free finance app is worth trying. Use it with a defined purpose, keep your accounting separate, and avoid treating the available balance as profit. If you want a universal bank, advanced bookkeeping, or one account for several kinds of gig work, I would choose a broader alternative instead.
For the right driver, that focused approach is exactly why the Uber Pro Card can be useful. It does not need to do everything. It needs to make one recurring part of working life—getting paid and handling that money—less tangled, and in my experience, that is where its strongest case lies.
Pros
- No monthly fee for standard card access.
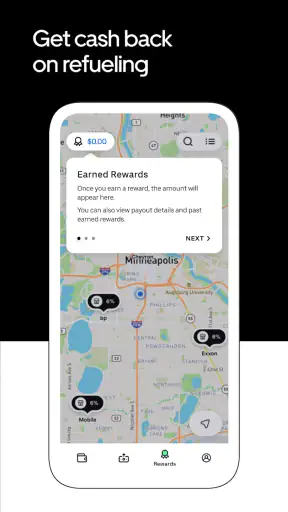
- Automatic cashback can help reduce everyday business costs.
- Instant access to eligible earnings improves cash flow.
- Built-in expense tracking simplifies separating work purchases.
- Accepted anywhere Visa debit cards are supported.
Cons
- Availability and benefits vary by country and driver eligibility.
- Cashback categories and rates may change over time.
- Some ATM withdrawals can incur fees or have limits.
- It is designed mainly for Uber drivers, not general users.
- Support may be slower for card-specific account issues.
FAQs for Uber Pro Card
What is the Uber Pro Card?
The Uber Pro Card is a financial account and debit card designed for eligible Uber drivers and delivery people. It can help you receive earnings, manage work-related money, and access features such as automatic payouts or cash-back opportunities, depending on your location and current Uber program terms. Availability, benefits, and account services may vary by country.
Who is eligible to apply for the Uber Pro Card?
Eligibility generally depends on your status as an active Uber driver or delivery person, your location, and the requirements set by Uber and its financial-services partner. You may need to meet certain activity or account conditions and complete identity verification. The app or Uber Driver account should show whether the offer is available to you before you begin registration.
Does the Uber Pro Card have monthly fees or other charges?
The Uber Pro Card is commonly promoted without a monthly maintenance fee, but users should still review the current fee schedule carefully. Charges may apply to specific services, such as out-of-network ATM withdrawals, expedited transfers, replacement cards, or transactions outside supported regions. Fees and terms can change, so confirm the details during enrollment.
How do I receive my Uber earnings with the Pro Card?
After activation and successful account verification, eligible users may be able to direct Uber earnings to the Pro Card account or use supported payout features. Processing times can depend on the type of earnings, weekends, banking networks, and local regulations. Before relying on the card for immediate expenses, check the payout status and applicable limits in the app.
Is the Uber Pro Card a credit card, and is my money protected?
The Uber Pro Card is generally a debit or spending card connected to a financial account, not a traditional credit card, so it normally does not provide a line of credit or build credit in the same way. Account protections, deposit insurance, dispute procedures, and card-network rules depend on the issuing partner and your country. Read the account agreement before depositing or spending money.

Uber Pro Card
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via ubersupport@branchapp.com, visit https://uberprocard-web.app.link/e/support-help-center, or review their https://www.branchapp.com/upc/privacy-policy.










